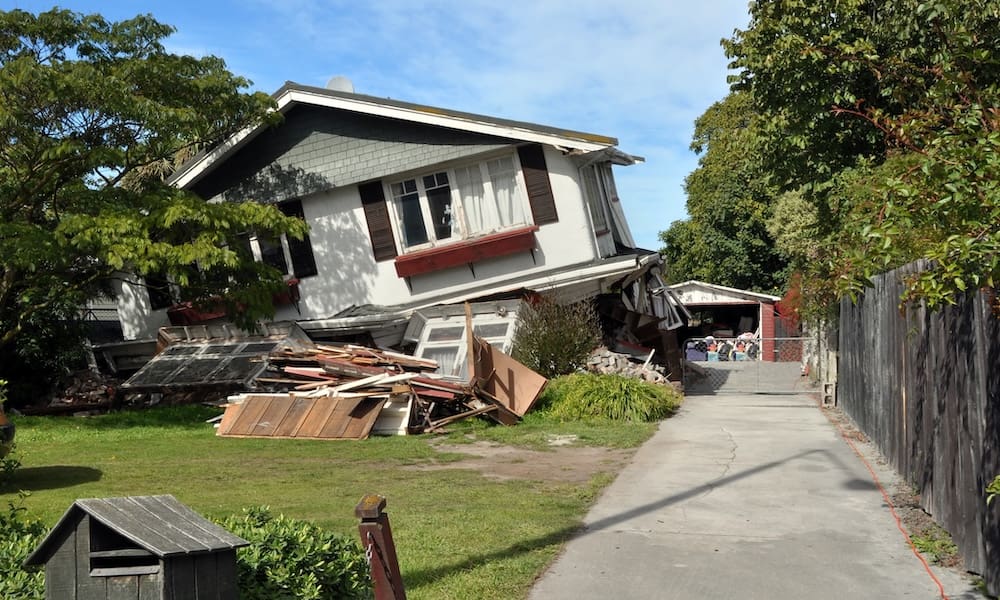
Could an Earthquake Damage Your Home?
When people think about earthquakes in the United States, they often think about the West Coast. But earthquakes can occur across the country. A standard homeowners insurance policy generally excludes earthquake or earth-movement damage, so homeowners should understand whether separate coverage or an endorsement is available.
Why Doesn’t Standard Homeowners Insurance Cover Earthquakes?
Homeowners policies cover many sudden and accidental losses, but they also include exclusions. Earth movement is commonly one of them. The exact exclusion varies by policy and may address earthquakes, tremors, earth sinking, rising or shifting earth, landslides, or other forms of earth movement.
What Does Earthquake Insurance Cover?
Depending on the policy, earthquake insurance may cover covered damage to the dwelling, certain personal property, and additional living expenses if covered earthquake damage makes the home temporarily uninhabitable. Limits and exclusions may apply.
Earthquake Coverage Example
Imagine an earthquake causes significant structural damage to your home, including cracks in portions of the foundation and damage to interior walls and belongings. Without earthquake coverage, the standard policy’s earth-movement exclusion could mean the earthquake damage itself is not covered. Appropriate earthquake coverage may respond subject to its deductible, limits, conditions, and exclusions.
What About a Fire After an Earthquake?
A single event can involve more than one cause of damage. An earthquake itself may be excluded under a standard homeowners policy, while a resulting fire may be treated differently depending on policy language and circumstances. Report losses promptly so the insurance company can determine how the policy applies.
How Do Earthquake Deductibles Work?
Earthquake insurance may use a deductible different from the regular homeowners deductible. Some policies use a percentage deductible. For example, if $500,000 of applicable coverage were subject to a 10% deductible, that could represent $50,000, depending on how the particular policy applies the deductible.
Is Earthquake Insurance the Same as Flood Insurance?
No. Earthquake and flood insurance address different exposures. A homeowner concerned about natural disasters may need to evaluate several separate risks rather than assuming one policy covers everything.
Do You Need Earthquake Coverage If You Don’t Live in a High-Risk Area?
Consider earthquake activity in your area, your home’s construction and age, its foundation, rebuilding cost, your ability to absorb a major uninsured loss, available coverage, the deductible, and the premium. A lower probability does not mean there is no exposure.
Review the Earth-Movement Exclusion in Your Policy
Use your insurance review to ask whether earthquake damage is covered, whether earthquake coverage is available, what deductible would apply, what property would be covered, and what exclusions you should understand.
Have Questions About Earthquake Coverage?
Oberryman Insurance Agency can help you review your homeowners insurance, explain the earth-movement exclusion, and discuss whether earthquake coverage may be available for your situation.
Call Oberryman Insurance Agency at 703-986-0468 to request a homeowners insurance review and discuss available coverage options.
Insurance coverage, eligibility, limits, deductibles, exclusions, endorsements, and availability vary by insurance company, policy, property, state, and individual circumstances. This article is provided for general informational purposes and does not modify or replace the terms of an insurance policy. Please review your policy and contact a licensed insurance professional regarding your specific coverage needs. Earthquake coverage may be provided by endorsement or separate policy depending on the insurance program.